How to Sell a Home in Ocean City, NJ: A Seller's Guide for Cape May County's Family Resort Island
Derek Doernbach, Realtor®
Published September 24, 2026 · 12 min read
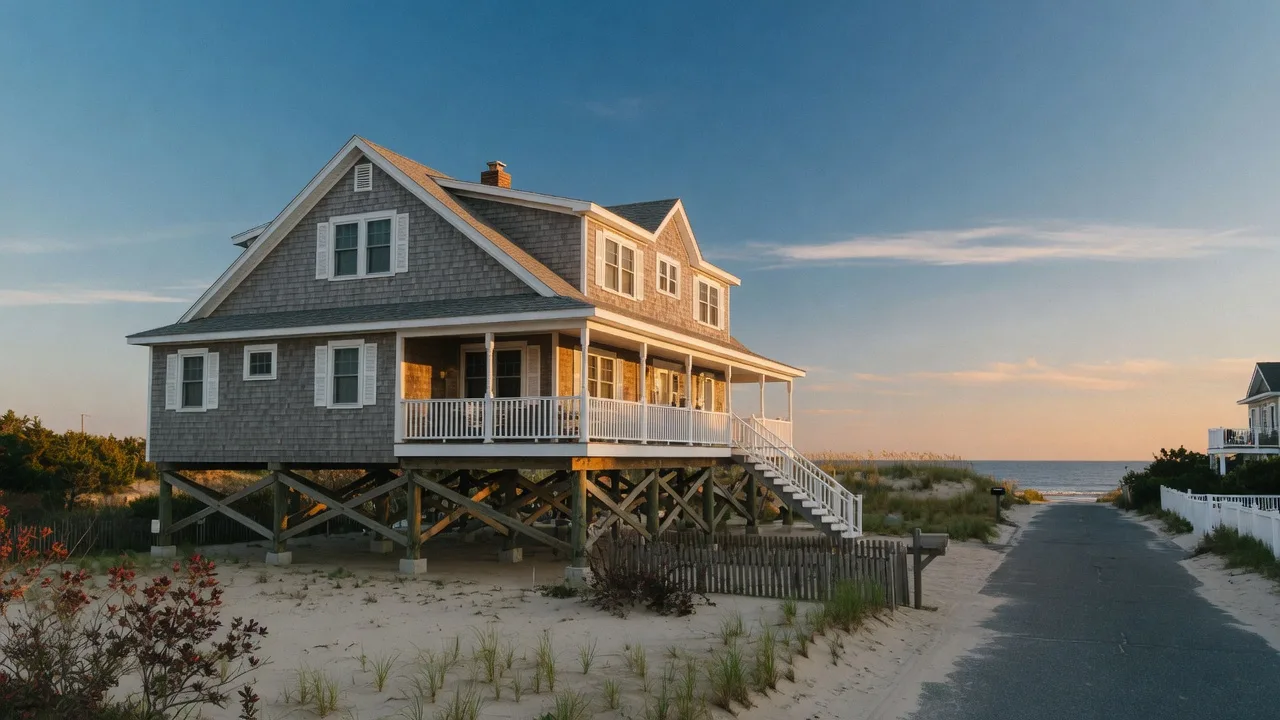
Selling a home in Ocean City, New Jersey does not require a certificate of occupancy for most resales, but it does require a fire-safety certificate from the city's Division of Fire Prevention before title can transfer, along with New Jersey flood disclosures and a pricing strategy built for a market where most of the island sits inside a FEMA flood zone.
Ocean City is the roughly eight-mile-long barrier island in Cape May County between the Atlantic Ocean and Great Egg Harbor Bay, incorporated in 1884 after being founded in 1879 as a Christian seaside resort. About 11,200 people live here year-round, the Ocean City School District serves the island from pre-K through grade 12, and a 2.5-mile boardwalk anchors the resort economy behind the city's long-held "America's Greatest Family Resort" nickname.
This guide is for homeowners and second-home owners thinking about selling in Ocean City, whether you own a beach-block bungalow, a bayfront home along the back bays, a longtime family shore house, or a property you currently rent to summer guests. The steps below cover the city paperwork, the flood questions, the rental-income questions, and the market realities that will shape your sale.
Key Takeaways
- Ocean City does not issue a separate resale certificate of occupancy for most existing homes, but sellers must obtain a fire-safety (smoke detector, fire extinguisher, carbon monoxide alarm) compliance certificate before title transfers
- Nearly the entire island is in FEMA flood zones (mostly AE, with limited VE along the oceanfront), so buyers with federally backed mortgages must carry flood insurance and will weigh elevation in their offer
- New Jersey's flood disclosure law requires you to disclose flood zone status, any past flood insurance claims, and any FEMA assistance received
- Many Ocean City buyers plan to rent the property, so current short-term rental rules (annual registration, liability insurance, the city's 3% platform-booking fee) directly affect the offers you receive
- With Ocean City's median sale price near or above $1 million, many sales trigger New Jersey's seller-paid Graduated Percent Fee, so factor it into your net expectations
Why Selling in Ocean City Is Different
Ocean City does not sell like a mainland town, and it does not sell like Atlantic County's barrier islands either. The buyer pool is a mix of year-round residents, second-home buyers from the greater New York and Philadelphia areas, and investors who see summer rental income as part of the purchase math. Properties span three broad segments: beach-block homes near the boardwalk and ocean, mid-island homes on the quiet residential streets, and bayfront homes along the back bays and lagoons that face the mainland and Great Egg Harbor Bay.
Reported market figures for Ocean City vary by data provider and reporting period, so treat any single number with caution. As of September 2026, Redfin reported an Ocean City median sale price near $1.4 million in early 2026 (up roughly 7.7% year over year), while other providers have reported medians closer to $850,000 to $1.1 million, and Zillow's average home value stood near $1.13 million (up about 10% year over year). Days on market have been reported in the range of roughly 100 to 115 days, with homes typically closing near or slightly below list price. Inventory has been reported around three months of supply.
The honest takeaway: Ocean City is a high-priced island market with a seasonal rhythm. Buying activity builds in late winter and peaks in late spring, as buyers race to have closing done in time for summer. Accurate pricing against recent island comps matters more than it does in lower-priced markets, because buyers here do their homework on flood insurance, elevation, and rental income before they ever make an offer.
What Ocean City Requires Before You Can Close
New Jersey does not have a statewide resale inspection requirement; each municipality sets its own rules. For Ocean City, the key requirement tied to a sale is a fire-safety certification, and the key thing not required is a separate resale certificate of occupancy for most existing homes.
The Fire-Safety Compliance Certificate
The city's Division of Fire Prevention requires a Smoke Detector, Fire Extinguisher, and Carbon Monoxide Alarm Compliance Certificate for the sale or transfer of title of residential units in one- and two-family dwellings and individually owned condo units. You apply through the city's "Application for Sale of Property Certificate" process, and the inspection verifies that working smoke detectors, carbon monoxide alarms, and fire extinguishers are in place before the sale closes.
Plan for this early. The certificate is tied to transfer of title, so a last-minute inspection finding of missing or expired detectors can delay your closing date. Putting fresh batteries in every detector, confirming CO alarms on each sleeping level, and having an accessible fire extinguisher ready before you list can save you a scheduling headache later.
No Resale Certificate of Occupancy for Most Homes
Ocean City's construction code office issues permits and inspects permitted work, but there is no published citywide requirement for a separate resale certificate of occupancy for existing homes. That said, municipal rules can change and some properties carry conditions from past permits, so your Realtor should confirm the current requirements for your specific address with the Ocean City Construction Code Office (861 Asbury Avenue, (609) 399-6111) before you list. If you are selling a condo unit, the same fire-safety certificate applies, and buyers and lenders will also review the association's resale package covering budgets, reserves, master insurance, and any pending special assessments.
Title and Bayfront Extras
For bayfront, lagoon, and back-bay properties, the title company will routinely run a tidelands and riparian search because parts of the shoreline may have been flowed by tide at some point in history, which can give the State of New Jersey an interest in the land. If a claim comes back, it is resolved as part of the closing, so it helps to know early rather than during attorney review.
Flood Zones, Elevation, and Flood Insurance
Flood exposure is the single biggest difference between selling in Ocean City and selling on the mainland, and it shapes everything from buyer financing to your list price.
Where the Island Sits on the Flood Maps
The city's own flood information makes the point directly: the entire island lies within a floodplain. Under the current FEMA Flood Insurance Rate Maps (effective October 5, 2017), most of Ocean City's populated areas are in Zone AE, the Special Flood Hazard Area with a 1% annual chance of flooding and established base flood elevations. Limited coastal areas along the oceanfront carry the higher-risk Zone VE designation, where wave action is a factor.
Because most financed sales in AE and VE zones require flood insurance, buyers will ask about it immediately. A seller who can hand over an elevation certificate showing the home's lowest floor relative to base flood elevation removes guesswork, can lower a buyer's insurance estimate, and strengthens the offer you receive. If you do not have one, obtaining it from a licensed surveyor before listing is usually worth the cost.
How FEMA's Risk Rating 2.0 Changes the Numbers
FEMA's Risk Rating 2.0, fully in effect since October 2022, prices flood insurance on individual property characteristics (distance to water, flood frequency, first-floor elevation, foundation type, replacement cost) rather than the flood zone letter alone. That means two beach-block homes in the same AE zone can have very different premiums. Buyers know this, and they will ask for your claim history and elevation data before they commit.
The Elevation Question: Do You Need to Lift Your House to Sell?
No. Existing homes in Ocean City are not required to be elevated just because they go on the market. New Jersey's coastal flood rules, updated by the NJDEP and finalized in January 2026, apply to new construction and to substantially improved or substantially damaged homes (generally, work equal to 50% or more of the building's market value). Those projects must be elevated to the Climate-Adjusted Flood Elevation, which is the FEMA base flood elevation plus four feet. Ocean City's own flood damage prevention ordinance (Chapter 21) adds local freeboard above the FEMA minimums for new work.
The practical effect for sellers: a newer elevated home is easier to finance and insure, and buyers usually price that in. An older, non-elevated home can absolutely sell, but the price discussion will include what an informed buyer expects to spend on insurance, and whether the home would someday need to be lifted after substantial work. Be ready for that conversation with honest numbers rather than defensiveness.
Your Flood Disclosures Are Not Optional
New Jersey law (S3110/A4783, effective March 20, 2024) requires residential sellers to disclose, in the Property Condition Disclosure Statement:
- Whether the property is in a FEMA Special Flood Hazard Area (1% annual chance) or a 0.2% annual chance floodplain
- Whether you have ever filed a flood damage claim with any insurance provider
- Whether you have received FEMA assistance for flood damage to the property
On an island where the entire municipality sits in a floodplain, this disclosure form is routine, not alarming. The risk is in getting it wrong. If you are unsure about your claim history, your insurance carrier can provide it, and the FEMA Map Service Center confirms your current flood zone. Full disclosure protects you from liability after closing and builds buyer trust.
How Short-Term Rental Rules Affect Your Buyer Pool
A large share of Ocean City buyers intend to rent the property for at least part of the summer, so the city's rental rules are part of your sale, whether you rent your own home today or not. Buyers will ask what income a property can produce and what it costs to operate it legally.
Ocean City treats dwellings rented for fewer than 175 consecutive days as short-term rentals under the state's definition, and every rental property must carry an annual rental registration and mercantile license. The registration year runs July 1 through June 30. For a single-family or two-family unit rented less than 175 days and not occupied by the owner, the combined annual fee is currently $175 ($30 mercantile license plus $145 municipal tourism assessment). Owners must also carry at least $500,000 in liability insurance and pass the same smoke detector, carbon monoxide alarm, and fire extinguisher certification required at sale.
The newer wrinkle is Ocean City's 3% "transient accommodations fee" on short-term rentals booked through online platforms such as Airbnb and Vrbo. Passed by City Council in July 2025 and effective in time for the 2026 season, the fee is paid by the renter on top of New Jersey state sales tax and the state occupancy fee, on platform bookings (traditional agency and phone bookings are exempt). Airbnb has publicly disputed the tax's legality, so its long-term status is worth watching, but it is law in effect today and it changes the income math for platform-booked rentals.
If you read about a moratorium on new short-term rental licenses and five-night minimum stays for Ocean City, note that those rules belong to Ocean City, Maryland, not the New Jersey island. For your sale, the practical point is simple: gather your rental registration, insurance proof, and rental history if you have them. A buyer looking at income projections will reward a clear, legal, documented rental picture.
Property Taxes and the Appeal Window
Ocean City property owners pay tax to the city and a share to Cape May County, and the county has no uniform revaluation calendar: assessments are adjusted and monitored year to year. If you believe your assessment is out of line with what the island is actually selling for, Cape May County homeowners can appeal to the Cape May County Board of Taxation during the annual filing window, typically in the spring.
For a sale, the appeal question usually works in reverse: if your home is over-assessed, an appeal can lower your carrying costs while you wait to sell, and it gives you a clean, defensible tax number to show buyers who will be estimating their own tax bill. If you are considering an appeal, act before the deadline, because the window closes every year.
Pricing, Marketing, and the Over-$1 Million Fee
Set the Price Against the Island, Not the Mainland
Ocean City pricing is driven by beach blocks, bayfront, and condition relative to elevation. A beach-block home with ocean views commands a very different number than a mid-island home a few streets back, and an elevated newer build out-prices an identical non-elevated older home because buyers fold insurance and future elevation costs into their offers. Your Realtor should build a comparable market analysis from recent Ocean City and nearby Cape May County shore sales, not from mainland zip codes.
The Graduated Percent Fee on Sales Above $1 Million
Because Ocean City's median sale price sits near or above $1 million, a large share of island sales triggers New Jersey's Graduated Percent Fee, the seller-paid transfer tax that replaced the mansion tax on sales over $1 million in 2024. The fee uses rate tiers that climb as the sale price rises, and it is paid out of the seller's proceeds at closing. Before you set your asking price or plan your net, confirm which tier applies and build it into your expectations along with existing closing costs.
Market to Buyers Who Aren't in the Room
A big share of Ocean City's buyers come from the New York, Philadelphia, and wider mid-Atlantic markets, which means many of your most serious prospects first see your home on a screen. Professional photography, walk-through video, aerial footage, and a Matterport 3D Digital Twin tour let a buyer evaluate the view, the layout, the deck, and the street before spending a weekend driving to the shore. In a market with this much competition at this price level, presentation quality is not a luxury; it is what separates a listing that draws multiple offers from one that sits.
What This Means for Sellers: Your Action List
- Start the fire-safety certificate process early. It is tied to transfer of title, so verify detectors, CO alarms, and fire extinguishers, and file the sale of property application before you have a contract.
- Assemble your flood file: your flood zone from the FEMA Map Service Center, an elevation certificate if you have one, and a clear record of any past claims for disclosure.
- Know your rental story. If you rent the property, pull together the registration, insurance, and income history; if you do not, be ready for buyers who have already priced what rental income could be.
- Calculate the Graduated Percent Fee for your likely price range so your net number is realistic from day one.
- Confirm your address's specific requirements with the Ocean City Construction Code Office and, for condos, the association's resale package requirements.
Frequently Asked Questions About Selling in Ocean City, NJ
Does Ocean City, NJ require a certificate of occupancy to sell a house?
There is no published citywide requirement for a separate resale certificate of occupancy for most existing homes in Ocean City. What the city does require before transfer of title is a fire-safety compliance certificate covering smoke detectors, fire extinguishers, and carbon monoxide alarms. Rules can change and individual properties can carry permit conditions, so confirm the specifics for your address with the Ocean City Construction Code Office.
What is the fire-safety certificate for selling an Ocean City home?
It is a Smoke Detector, Fire Extinguisher, and Carbon Monoxide Alarm Compliance Certificate issued through the city's Division of Fire Prevention via the Application for Sale of Property Certificate. The inspection confirms working smoke detectors, carbon monoxide alarms, and fire extinguishers in the residential unit before title transfers. File early so the certificate is ready before closing.
Do I need to elevate my Ocean City house to sell it?
No. Existing homes are not required to be elevated just to be sold. New Jersey's coastal flood rules, finalized in January 2026, require new construction and substantially improved or substantially damaged homes to be elevated to the base flood elevation plus four feet. Buyers still factor insurance cost and future elevation potential into their offers, so be prepared to discuss it.
What flood disclosures do Ocean City sellers have to provide?
Under New Jersey's flood disclosure law, effective March 2024, sellers must disclose whether the property is in a FEMA Special Flood Hazard Area or 0.2% annual chance floodplain, whether they have ever filed a flood damage claim, and whether they have received FEMA assistance for flood damage. On an island wholly within a floodplain, this is routine, but it must be accurate.
How do short-term rental rules affect selling an Ocean City property?
Many buyers purchase Ocean City homes intending to rent them, so they will ask about annual rental registration (currently $175 for a single- or two-family unit rented under 175 days and not owner-occupied), the $500,000 liability insurance requirement, the fire-safety certification, and the 3% city fee on platform bookings that took effect for 2026. A clean, documented rental history supports a higher offer; missing paperwork raises questions.
What is the best time of year to sell in Ocean City, NJ?
The strongest window is generally late winter through late spring, when buyers are trying to close in time for summer. Well-priced, well-marketed island homes sell year-round, but listing in February through April gives you the largest pool of motivated seasonal buyers and the longest runway to a summer closing.
If you are thinking about selling a home in Ocean City, Cape May County, or anywhere along the South Jersey shore, I can walk you through your home's realistic value on the island market, the city's resale requirements, and a marketing plan built for out-of-area buyers. It costs nothing to get the real numbers.
Derek Doernbach, Realtor®
Century 21 Action Plus Realty | Your Jersey Shore Team
Derek has been helping South Jersey families buy and sell homes since 2016. He has closed 192 transactions and earned the New Jersey Realtors® Circle of Excellence Award every year since 2019. He helps sellers throughout Atlantic County, Cape May County, and the Jersey Shore prepare, price, and market their properties with professional photography, video, and Matterport 3D Digital Twin tours. Licensed in New Jersey (1645208).
Sources and References
- City of Ocean City, NJ: Division of Fire Prevention: Smoke Detector, Fire Extinguisher, and CO Alarm Compliance Certificate (services.ocnj.us, accessed September 2026)
- City of Ocean City, NJ: Construction Code Office (services.ocnj.us, accessed September 2026)
- City of Ocean City, NJ: Flood Hazards and Maps (ocnj.us/flood-hazards-maps, accessed September 2026)
- City of Ocean City, NJ: Home Elevation FAQs (ocnj.us/home-elevation-faqs, accessed September 2026)
- FEMA Flood Insurance Rate Maps for Cape May County, effective October 5, 2017; FEMA Flood Map Service Center (msc.fema.gov)
- NJDEP: proposed changes to coastal flood regulations, news release July 21, 2025; final coastal flood rules, January 2026
- Ocean City Revised General Ordinances, Chapter 21 (Flood Damage Prevention) and Chapter 30 Schedule A (mercantile and rental fees); N.J.S.A. 40:52-1(n) and N.J.S.A. 40A:10A-1
- Ocean City Council: 3% transient accommodations fee on platform short-term rental bookings, approved July 17, 2025, effective late 2025 (coverage: 6abc, Philadelphia Inquirer, Ocean City Sentinel; accessed September 2026)
- New Jersey Flood Disclosure Law (S3110/A4783, effective March 20, 2024)
- Redfin, Zillow, and Houzeo: Ocean City, NJ housing market data (accessed September 2026; figures vary by provider and reporting period)